Confidence and affordability pressures continue to hold back UK property market
Residential property transactions fell by 4% year on year in September
3 November 2026 | Author: Mark Cunningham
Seasonally adjusted residential property transactions fell by 4% year on year in September to 94,800
A subdued property market ahead of the Budget
The UK residential property market continues to face challenging conditions, with the latest HMRC figures highlighting the impact of weaker confidence and affordability pressures on activity.
Seasonally adjusted residential property transactions fell by 4% year on year in September to 94,800. Transactions were also marginally lower than in August, suggesting that the market remains subdued despite hopes of a recovery.
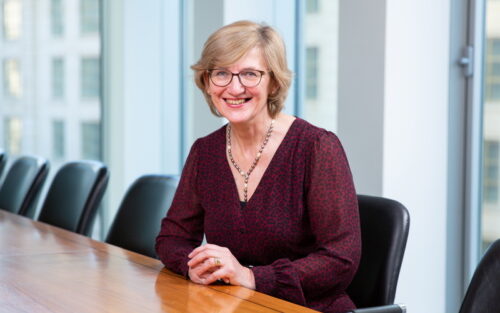
Mark Cunningham, Partner, said:
HMRC’s figures for UK residential transactions in September show that confidence and affordability pressures are continuing to hold back activity, with the property market being particularly subdued before the Autumn Budget. Seasonally adjusted residential transactions were down 4% year on year to 94,800 and were also marginally lower than in August
The figures reflect a housing market where potential buyers and sellers remain cautious. Economic uncertainty, the cost of living and the prospect of further changes to taxation are all contributing to hesitation, while higher property prices continue to make home ownership difficult for many.
For businesses operating across the property sector, including estate agents, housebuilders, mortgage providers and property investors, subdued transaction levels can create further uncertainty around demand, investment and future growth.
Interest rates remain the biggest influence
Looking ahead, the direction of interest rates is likely to be one of the most significant factors determining the strength of the property market over the next 12 months.
The months to come will show us how the market responds to the Chancellor’s announcements, but the biggest influence on transactions over the next year is likely to be the direction of interest rates. With further rate rises expected, higher borrowing costs will put renewed pressure on affordability and confidence, making an already challenging market even more difficult. The expected rises are being driven by global factors beyond the housing market, but homeowners and buyers will feel this through higher mortgage costs.
Higher mortgage rates can affect both affordability and confidence. For prospective buyers, increased monthly repayments may mean borrowing less, delaying a purchase or reconsidering the type of property they can afford. Existing homeowners coming to the end of fixed-rate mortgage deals may also face higher repayments, potentially limiting their ability to move.
This creates a difficult environment for the wider housing market, as fewer buyers may be able or willing to commit to a purchase.
Tax changes could prompt more landlords to sell
The further rise in tax on property income to 24%, 44% and 49% announced in the Budget will be the final straw for many landlords, and lead some to sell up. This should increase the supply of homes coming to market and may increase transaction numbers in the coming months, but that should not be mistaken for a healthier property market driven by real growth and buyer demand.
If more landlords decide to exit the market, additional properties could become available for sale, potentially increasing transaction numbers.
However, there is an important distinction between increased activity caused by landlords selling their investments and genuine growth in demand from buyers. A rise in transactions does not necessarily indicate that affordability is improving or that confidence is returning.
For tenants, the longer-term consequences are also worth considering. A reduction in the supply of privately rented homes could create further pressure on rental availability, particularly in areas where demand already exceeds supply.
Can the Your First Home scheme support a recovery?
The Government’s Your First Home scheme could provide some additional support for prospective buyers, particularly those struggling to save enough for a deposit.
By helping some buyers overcome this initial financial barrier, the scheme has the potential to support transaction levels and, over time, encourage additional housebuilding.
However, its impact is unlikely to be immediate. The costs associated with participating in the scheme could also influence how widely it is adopted and how many buyers ultimately benefit.
Mark concluded:
The Your First Home scheme should help some buyers overcome the deposit barrier and support transactions and, over time, some additional new build delivery. However, the effect will not be immediate and, given the costs of participation, it remains to be seen how significant its impact will ultimately be
While initiatives aimed at improving access to home ownership are welcome, they cannot address all the challenges facing the property market. The availability of suitable housing, mortgage affordability and wider economic confidence will remain important factors in determining whether activity can recover sustainably.
What should buyers, homeowners and landlords consider next?
The outlook for the UK property market remains uncertain, and the coming months will provide a clearer indication of how buyers, sellers and investors respond to the Autumn Budget measures.
For individuals considering buying or selling, it will be important to assess affordability carefully, particularly if mortgage rates increase further. Prospective buyers should consider how changes to borrowing costs could affect their monthly commitments, rather than basing decisions solely on current rates.
Landlords should review the financial performance of their portfolios in light of the changes to property income taxation, taking account of financing costs, ongoing expenses and potential rental returns. For some, selling may become a more attractive option, although the tax implications of doing so should be considered before making a decision.
For businesses operating in the property sector, monitoring transaction volumes, interest rate expectations and changes in landlord behaviour will be important when assessing market demand and planning for the year ahead.
Ultimately, a sustainable recovery will depend on more than an increase in the number of properties changing hands. Improving affordability and restoring confidence will be essential if the market is to move beyond its current subdued position.
Would you like to know more?
If you have any questions about the above, please get it touch with your usual Blick Rothenberg contact or Mark using the form below.
Contact Mark
Property & Construction Hub
Helping companies in the Property and Construction sectors adapt and maximise their opportunities for growth
An area where insights and articles into current news around the property industry are brought together and made easily accessible
You may also be interested in
Residential property market confidence remains low despite an improving economic outlook
Frozen SDLT Thresholds: Is Tax Holding Back the UK Housing Market?